The 60-second version
NRIs and PIOs can remit eligible NRO balances up to USD 1 million per April–March financial year, alongside their other eligible assets. Current income is a separate route. Account status must reflect your actual FEMA residence, not your preferred transfer timing.
Fast answer: USD 1 million is the eligible asset lane, not a cap on every receipt
The RBI permits NRIs and PIOs to remit eligible NRO balances up to USD 1 million per Indian financial year, April to March, along with their other eligible assets. Its account FAQ also allows NRO-to-NRE transfers within that facility. Separately, current income such as rent, dividend, pension and interest can be remitted abroad, subject to applicable tax and bank checks. These are different routes, not two names for the same allowance.
The important question is therefore not just how much is in the NRO account. It is where the money came from, whether you are still resident outside India under FEMA, how much of the eligible-asset allowance you have already used, and whether tax evidence supports the request. A large balance alone does not establish eligibility.
This is not the resident Liberalised Remittance Scheme. Do not call the NRO facility an LRS allowance, and do not assume the USD 1 million amount applies afresh to every bank account. The RBI wording aggregates eligible assets within the financial year. Ask your authorised-dealer bank to confirm the treatment of your particular source before converting currency or committing to an overseas purchase.
Choose the route before assembling forms
| Money or situation | Route to discuss with the bank | Key evidence |
|---|---|---|
| Current rent, pension, dividend or interest | Current-income remittance, subject to tax compliance | Income statement, source trail and applicable tax proof |
| Other eligible NRO balances and assets | USD 1 million financial-year facility, subject to Remittance of Assets regulations | Source documents, tax evidence and prior remittance declaration |
| NRO money transferred into your NRE account | Within the same USD 1 million facility | Your NRE details and usage of the facility this year |
| You have returned and become FEMA-resident | Resident-account and outward-remittance rules; do not assume the NRI route remains available | Actual return circumstances and updated bank KYC |
Form 15CA and Form 15CB are not interchangeable
The Form 15CB manual describes an accountant's certificate dealing with taxability, the applicable tax rate and tax deducted on the payment. It is not RBI permission to remit. The remitter's reporting and the accountant's certification serve different purposes; the bank still applies FEMA and source-of-funds checks.
Do not order a Form 15CB simply because a transfer exceeds an amount quoted in a bank discussion. Chargeability, the applicable Form 15CA part, exemptions and any assessing-officer certificate matter. Give your accountant the nature and amount of the remittance, proposed recipient, tax residence and supporting tax records, then obtain the documents that actually apply. A universal promise that every NRO transfer needs the same certificate is misleading.
For a property-sale balance, keep the sale deed, acquisition and inheritance evidence where applicable, capital-gain computation and tax-payment trail together. For rent, keep the rental statement and tax trail. If one transfer combines those sources, show the breakdown rather than describing the entire balance as current income.
A practical bank submission process
Confirm actual FEMA status
Tell the bank whether you still live abroad or have returned for employment, business or an uncertain stay. Do not use an unchanged account label as proof that you remain non-resident.
Reconcile the amount by source
Separate identifiable current income from other eligible balances. Record supporting documents and any earlier transfers under the asset facility in the same April–March year.
Get the bank's written checklist
Ask about the remittance application, beneficiary details, source declaration, tax documents and any additional checks for the asset involved. A different branch's anecdotal checklist is not binding.
Resolve tax reporting
Have your accountant determine the relevant reporting and certification. Supply statements and tax records before the intended transfer date, not after the bank rejects a request.
Compare net proceeds and retain evidence
Ask for the exchange rate, fees, correspondent deductions and expected value date. Save the remittance advice and bank statements showing the completed transfer.
Before the bank appointment
- Current identity, residence and account-status information
- A source-by-source reconciliation of the proposed amount
- Relevant sale, inheritance, income and tax records
- Prior remittances and NRO-to-NRE transfers under this year's facility
- Beneficiary details verified independently
- Written confirmation of the applicable tax documents and fees
Never delay required redesignation to preserve a remittance route
Returning for an uncertain stay changes the account-status question. Inform the bank promptly and follow the rules that match your actual residence. A pending outward payment is not a reason to keep using an NRO account as though you still live abroad. RNOR income-tax status does not itself preserve non-resident FEMA status.
Need help with Banking?
Share your blocker in one line. Our experts will reply with practical next steps.
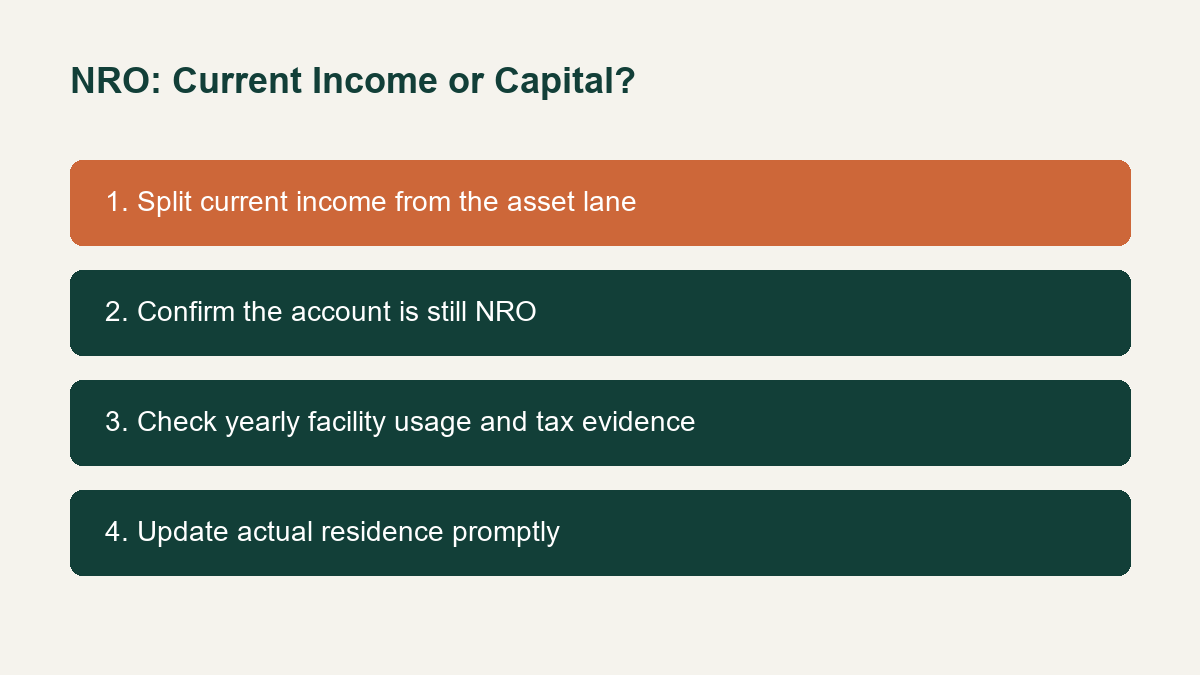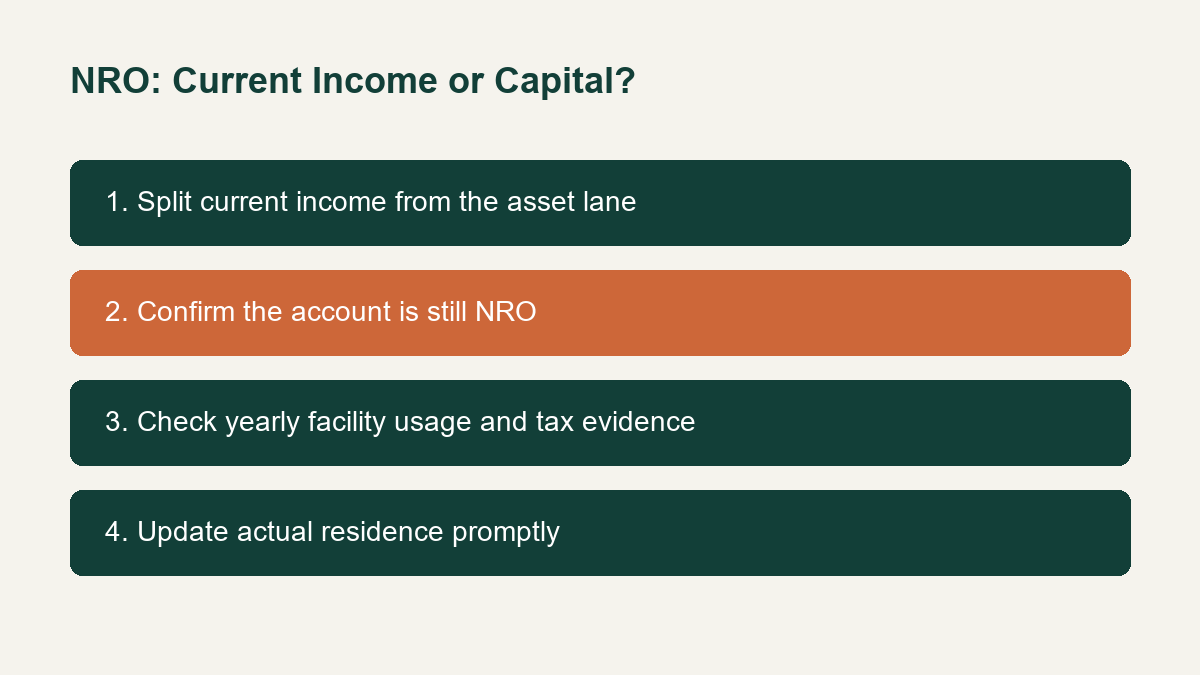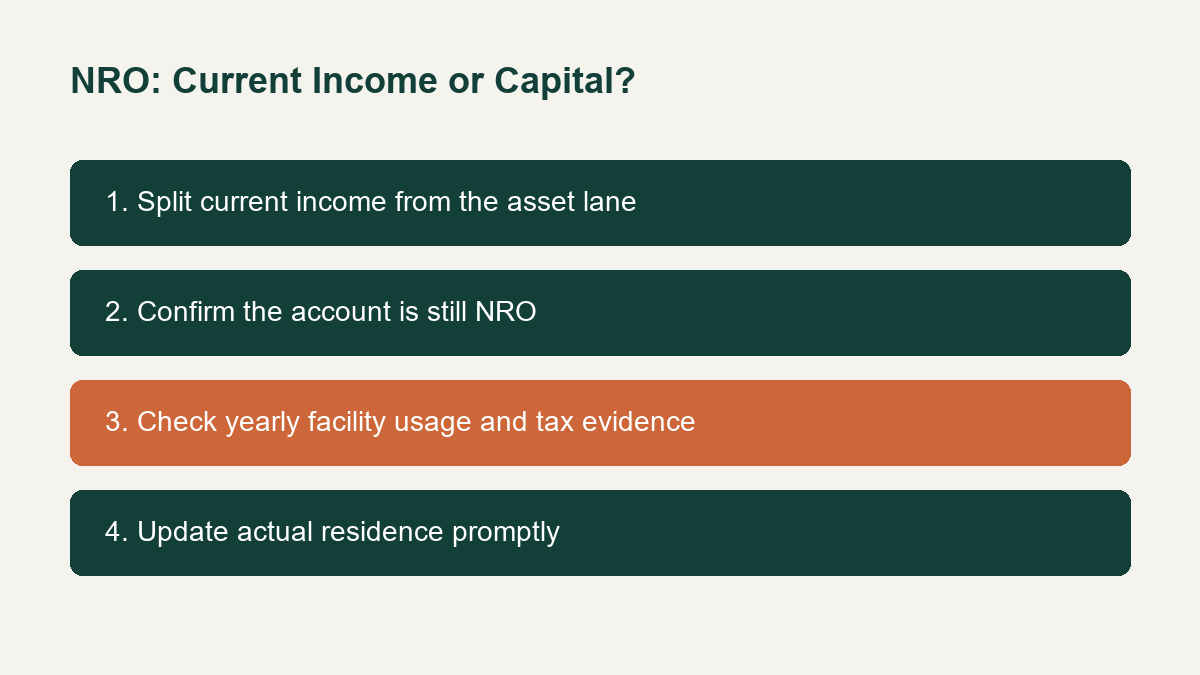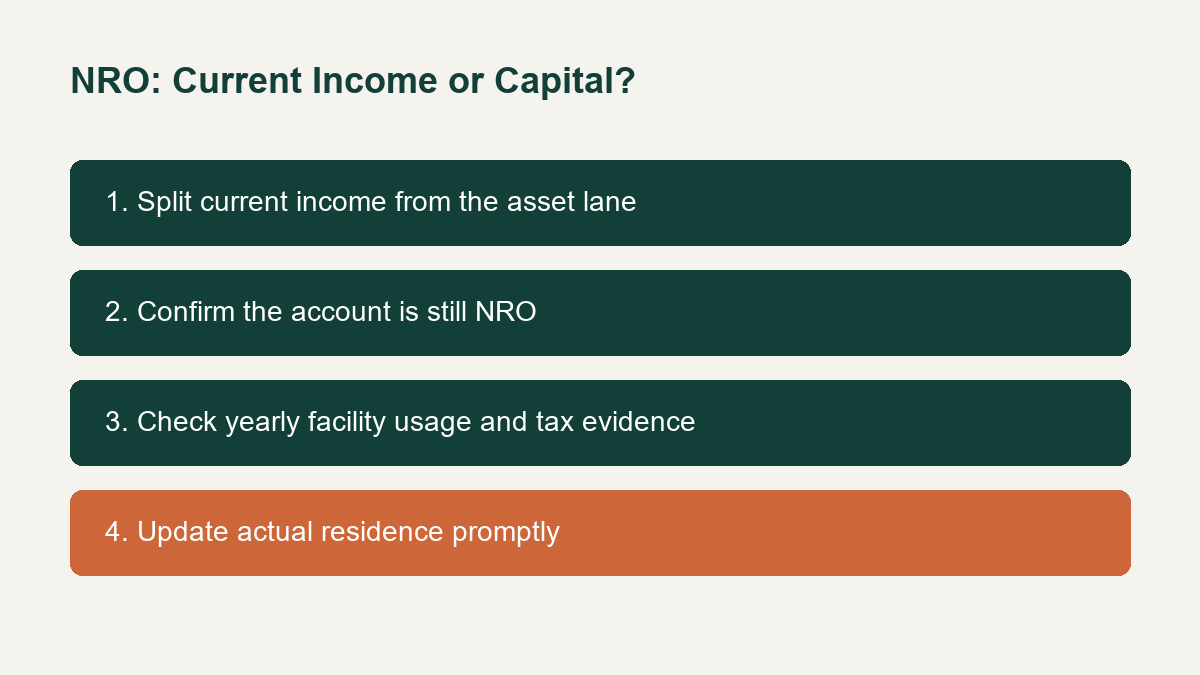
The decision before the transfer
NRO remittance preparation
Animated decision map
Community signal
What to watch in real discussions
Treat repeated complaints as risk signals rather than official advice. This page does not link to community search results.
Interactive checkpoint
Turn this guide into a decision file
0 of 4 checked
What is the NRO repatriation limit?
For NRIs and PIOs, eligible NRO balances are remittable up to USD 1 million per April–March financial year along with other eligible assets, subject to the Remittance of Assets regulations. Current-income remittances are treated separately.
Does an NRO-to-NRE transfer use that facility?
Yes. The RBI expressly places NRO-to-NRE transfers within the USD 1 million facility. It is not an additional allowance.
Is the limit per bank account?
Do not assume that. The RBI refers to the financial-year amount along with other eligible assets. Disclose prior facility usage across banks to your authorised dealer.
Is Form 15CB always required?
No universal rule covers every transfer. Applicable taxability, reporting, exemptions and any assessing-officer certificate affect the paperwork. Ask the bank and your accountant which reporting and certificate apply.
Can I stay NRO after returning so I can send the balance abroad?
Do not delay required account redesignation. Tell the bank your actual FEMA residence and have it assess the appropriate resident route if you have returned. RNOR tax status is a separate test.
Does a new financial year reset all conditions?
The amount is measured over April to March, but a new year does not remove source, eligibility, tax or residence conditions. The bank must still assess the remittance.
Your NRE account redesignation has a deadline.
Banks don't remind you. You need the right account stack before salary, rent, and EMIs start moving. Get the exact sequence.