The 60-second version
Rejections cluster into six causes: an unresolved KYC record, a PAN-Aadhaar mismatch, a joint holder whose status has not been updated, an active mandate or lien blocking redesignation, a dormant account with a frozen record, and a branch applying an internal product rule rather than a regulatory one. Five are fixable at the desk. Only the sixth needs escalation.
Get the reason in writing. That single step resolves most cases.
A refused conversion is almost never a regulatory prohibition. Converting an NRO account to a resident account when you have become resident is an ordinary service request. What the counter is actually telling you is that something in your file does not reconcile. Ask for the reason in writing and the case stops being a conversation about policy and becomes a specific defect you can fix.
The causes cluster. A stale KYC record still describing you as a non-resident. A PAN-Aadhaar mismatch, which fails a live validation check rather than a rule. A joint holder whose own status has not been updated, so the mandate cannot be re-recorded. A lien, hold or live standing instruction attached to the account that blocks the designation change. A dormant account whose record has been archived. Or, the only one that needs escalation, a branch applying an internal product rule as though it were a regulatory requirement.
Five of those six have a concrete fix that you can perform. The sixth is where you use the grievance ladder: the branch's written refusal, then the bank's nodal officer, then the banking ombudsman. Do not skip the written-refusal step — every later rung in that ladder asks for it.
If the answer you get is 'close the account and open a new one', treat that as a red flag rather than a solution. The correct route is in the conversion guide, and closing the account transfers the bank's compliance problem onto your transaction history.
Cause, fix, and whether to escalate
Find your symptom, apply the fix, and escalate only on the last row.
| Symptom | Actual cause | Fix | Escalate? |
|---|---|---|---|
| 'Status mismatch on file' | KYC record still says non-resident | Submit the status declaration and get the record refreshed | No |
| Validation failure at the counter | PAN not linked to Aadhaar, or details differ | Correct the link and the name and date-of-birth details at source | No |
| 'Joint holder details required' | Co-holder's status or KYC is stale | Get the co-holder's declaration or notarised form | No |
| 'Account has a hold' | Lien, freeze, or live mandate blocks redesignation | Identify the specific hold, resolve it, then re-submit | No |
| 'Record not available' | Dormant or archived account | Reactivate the record first, then request redesignation | No |
| 'We do not do that' with no defect named | Internal product rule applied as policy | Request the refusal in writing and cite the service request | Yes — nodal officer, then ombudsman |
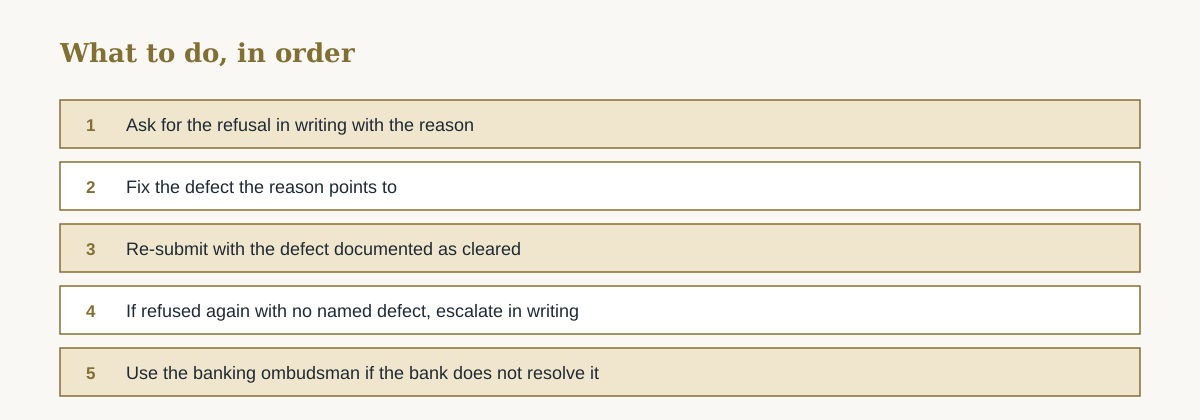
What to do, in order
Each step produces the document the next step needs. Do not skip ahead.
Ask for the refusal in writing with the reason
A named reason, not a summary. If the branch will not put it in writing, note the date, the person and what they said, then move up one level.
Fix the defect the reason points to
Every named reason maps to one row of the table above. Work that row's fix rather than arguing about the outcome.
Re-submit with the defect documented as cleared
Attach the evidence that the specific defect is resolved. Re-submissions that do not identify what changed get treated as fresh applications.
If refused again with no named defect, escalate in writing
Write to the bank's nodal officer for the grievance, enclosing the original refusal and the corrected documents. Keep it factual and dated.
Use the banking ombudsman if the bank does not resolve it
The ombudsman route exists for exactly this. Attach the written refusal, the escalation and the proof that the defect was cleared.
Parallel-track the rest of the sweep meanwhile
Do not let one bank stall the demat, folio and insurer updates. Work the other records while this one is in dispute.
Dispute file
Assemble this as you go, not afterwards.
- Written refusal naming the specific reason
- Date, branch, and the name of the person who refused
- Evidence that the named defect has been cleared
- Copy of the original service request form
- Bank acknowledgement of every submission
- Escalation letter to the nodal officer, dated
- Note of any parallel record that is also waiting on this
Five fixes, one escalation
Need help with Banking?
Share your blocker in one line. Our experts will reply with practical next steps.
Community explainer: the rule the branch cites
"What the bank is obliged to check, useful context when you are told something is not allowed."
Read on youtube ->Podcast: status change and the account that follows
"The status transition explained end to end, which is the fact pattern the branch is trying to record."
Read on youtube ->Escalation ladder
Need help with Banking?
Share your blocker in one line. Our experts will reply with practical next steps.
Refuse the 'close and reopen' suggestion
Closing the NRI account and opening a fresh resident account destroys your transaction history, standing instructions and credit continuity, and it solves the bank's record problem rather than yours. Redesignation on the same account number is the correct service request.
The one-sentence answer
Ask for the refusal in writing, fix the specific defect it names, re-submit with proof, and escalate to the nodal officer and then the banking ombudsman only when the bank cannot name a defect at all.
Animated decision map
Need help with Banking?
Share your blocker in one line. Our experts will reply with practical next steps.
Which account change applies to you?
Four questions. You get the course of action, in order, for your situation.
Question 1 of 4
Interactive checkpoint
Turn this guide into a decision file
0 of 4 checked
Can a bank refuse to convert my NRO account to a resident account?
The branch can stall on a defective file, but redesignation is an ordinary service request once you are resident. A refusal should come with a specific reason you can act on.
What if the branch says the system does not allow it?
Ask which field or record the system is rejecting, and for the refusal in writing. A system limitation is usually a symptom of a stale KYC record rather than a rule against conversion.
My PAN details do not match. What do I fix?
The name spelling and the date of birth on the PAN and Aadhaar records have to match. Correct the source record rather than asking the bank to work around the mismatch.
The branch insists I close the account instead. What should I do?
Decline and request redesignation on the same account number. Closing loses your standing instructions, transaction history and credit continuity, and it is not the correct route.
How do I escalate a bank grievance in India?
Write to the bank's designated nodal officer with the written refusal and the evidence the defect is cleared. If the bank does not resolve it, take it to the banking ombudsman for your jurisdiction.
Can a lien or a standing instruction really block conversion?
A hold, lien or live mandate can prevent the designation from being changed. Identify the specific block, resolve it, and then re-submit the request.
My account is dormant. Does that change anything?
It changes the order of work. Reactivate the record first, then request the redesignation. Asking for a conversion on an archived record is why some branches report 'record not available'.
What if my joint holder is abroad and cannot sign?
Banks commonly accept a notarised and attested form, but requirements vary. Confirm with the branch in advance rather than discovering the requirement at the counter.
How long should a conversion take?
A clean file is often handled the same day. Elapsed time beyond that is almost always documentary, which is why the written reason matters so much.
Does a rejected conversion affect my other accounts?
It should not, and that is why you should keep working the demat, folio and insurer updates in parallel instead of waiting for one branch to resolve.
Your NRE account redesignation has a deadline.
Banks don't remind you. You need the right account stack before salary, rent, and EMIs start moving. Get the exact sequence.