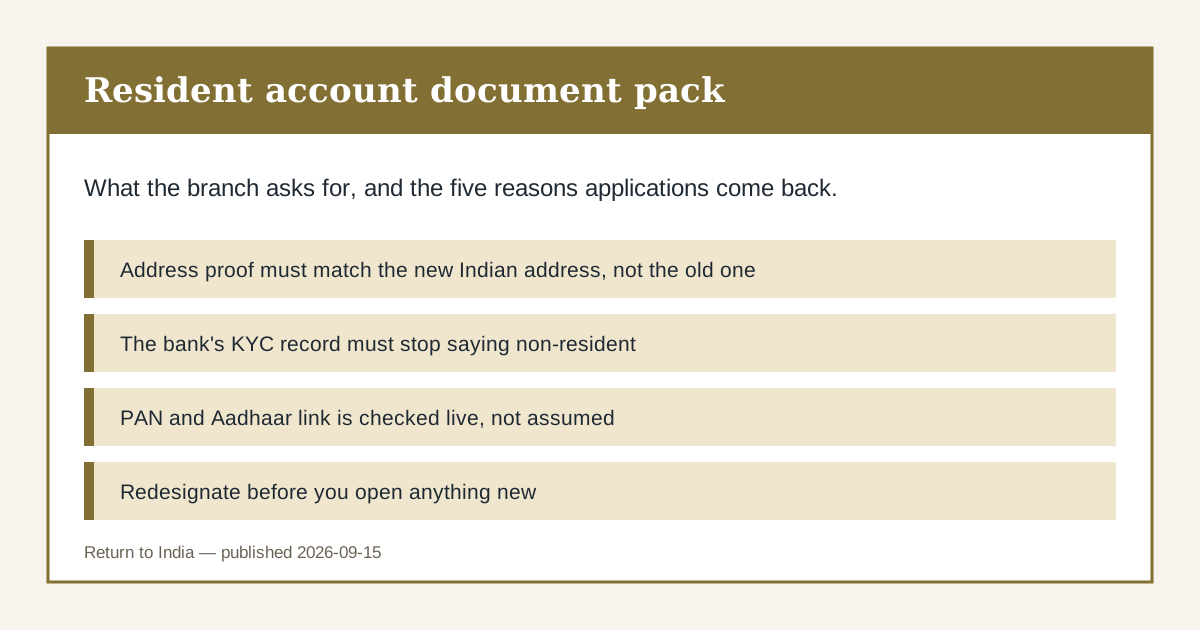
The 60-second version
A returned NRI needs proof of identity, proof of address that matches the new Indian address, proof of the change of status, and a PAN-Aadhaar link that actually verifies. Rejections cluster in five places: address mismatch, KYC record still recording non-resident status, dormant accounts, unlinked PAN, and a joint holder whose own KYC is stale.
Four document groups, and one record the bank has to change
The document request is smaller than people expect. Banks want identity, address, tax and status. Identity is PAN plus Aadhaar plus passport. Address is proof of where you now live in India — and this is where most applications stall, because a passport still carrying a foreign address or a utility bill in a relative's name does not satisfy the address rule for a fresh KYC record.
Tax means PAN with the Aadhaar link verified and, where the account is large or the profile warrants it, your recent return. Status means the evidence that you have ceased to be a person resident outside India — the entry record, the employment or relocation document, or the declaration you signed for the redesignation.
Then there is the fifth requirement that is not a document at all: the bank's own KYC record has to be updated. Redesignation of an existing NRO account is the cheapest way to achieve that, because it forces the record to be refreshed without opening anything. That is why the conversion route is almost always better than a fresh account.
A returned NRI can hold a resident savings account. What you cannot do is hold a non-resident account and operate it as though nothing changed. The account rule book sets out which of your existing accounts survive the change and in what form.
Document pack by purpose
Two routes exist. Take the left column if you already bank in India; the right column only if you do not.
| Document | Redesignation (existing account) | Fresh resident account | Common failure |
|---|---|---|---|
| PAN | Required | Required | Not linked to Aadhaar, so the check fails live |
| Aadhaar | Required | Required | Address on Aadhaar still shows the old Indian address |
| Passport | Required | Required | Foreign address on the last page used as address proof |
| Address proof in India | Required | Required | Rent agreement in a family member's name only |
| Status evidence | Declaration plus entry record | Declaration plus entry record | Verbally explained instead of documented |
| Signature and photo | Re-signed on the mandate | Fresh specimen | Signs differently from the record on file |
| Nomination | Re-recorded | New form | Left blank, then queried at activation |
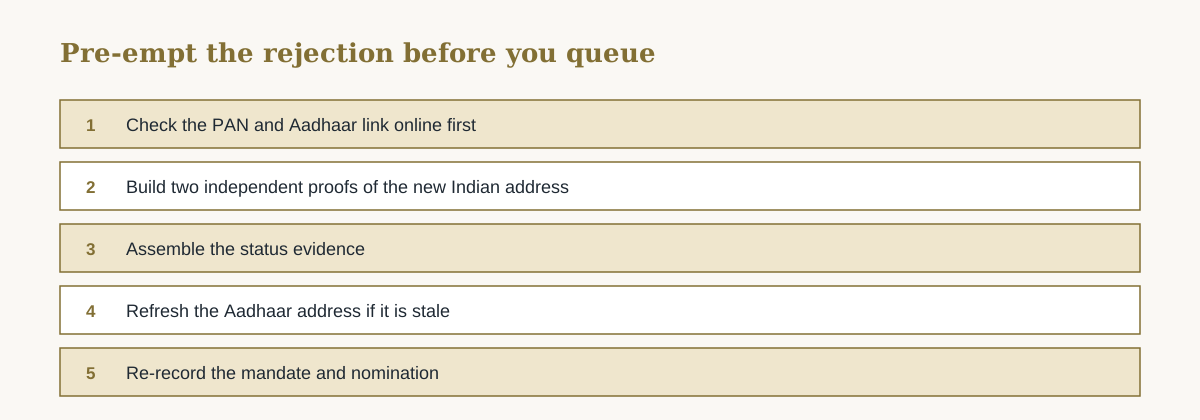
Pre-empt the rejection before you queue
Half an hour of preparation removes most of the back-and-forth.
Check the PAN and Aadhaar link online first
Verify the link yourself before the branch does. If it is not active, fix it at the source; an unlinked PAN is the most common live-check failure.
Build two independent proofs of the new Indian address
A rent agreement or ownership document plus one utility or bank statement carrying the same address. Two sources end the argument at the counter.
Assemble the status evidence
Entry stamp, relocation letter or a signed declaration setting out your residency date. Have it ready in writing rather than describing it verbally.
Refresh the Aadhaar address if it is stale
If the Aadhaar still shows an address you abandoned years ago, update it. It is the record most other verifications lean on.
Re-record the mandate and nomination
Joint holders and nominees carry a status field too. Bring the second holder or their signed form so the account activates without a second appointment.
Branch pack
Print this and tick it physically. It is faster than remembering.
- PAN card with the Aadhaar link confirmed active
- Aadhaar with an address that matches where you actually live now
- Passport with the entry record showing the move
- Two independent proofs of the current Indian address
- Written residency date and the document that supports it
- Nomination form, completed rather than left blank
- Joint holder's signature or attendance if the account is joint
- Bank's acknowledgement naming every account touched
Where applications stall
Document-to-activation path
Need help with Banking?
Share your blocker in one line. Our experts will reply with practical next steps.
A stale Aadhaar address sinks the application
Aadhaar is the record most other verifications lean on. If it still shows an address you left years ago, the branch cannot reconcile it against your rent agreement, and the file stops there. Update it before you apply, not after.
The one-sentence answer
The pack is PAN with an active Aadhaar link, two proofs of the new Indian address, written status evidence, and a re-recorded mandate — and the cheapest route is redesignating your existing NRO account rather than opening anything new.
Animated decision map
Which account change applies to you?
Four questions. You get the course of action, in order, for your situation.
Question 1 of 4
Community signal
What to watch in real discussions
Treat repeated complaints as risk signals rather than official advice. This page does not link to community search results.
Interactive checkpoint
Turn this guide into a decision file
0 of 4 checked
Can an NRI hold a resident savings account in India?
A person who is a non-resident should not be operating an ordinary resident savings account as their primary account. Once you become resident, a resident savings account is exactly the right account to hold.
What documents do I need to open a resident savings account after returning?
PAN with an active Aadhaar link, Aadhaar, passport with the entry record, two proofs of your current Indian address, evidence of the change of residency status, and a completed nomination form.
Can I just keep using my old resident savings account that I never closed?
If it was genuinely dormant or was being held improperly while you were non-resident, expect the bank to want the record refreshed. Reactivating it is usually simpler than opening a new account, but do it deliberately rather than by resuming transactions.
Is there a minimum balance requirement?
It depends on the bank and the account variant. Complaints about minimum balance almost always concern the specific product chosen, not a rule of the conversion process, so compare variants before you commit.
Why was my application rejected for having a foreign address?
Because address proof has to evidence where you live now. A passport page showing your former overseas address is not proof of an Indian residence, even though the passport itself is valid identification.
Do I need to update my Aadhaar address first?
If it is stale, yes. It is the document the verification rests on, and an inconsistency between Aadhaar and your other proofs is treated as a red flag rather than a clerical issue.
What if my joint holder is still abroad?
The joint holder's status may not have changed, which affects operating rights and mandates. Bring their signed form or plan for a joint process; banks will not re-record a joint mandate unilaterally.
Do I need to show my income tax return?
Not usually for a savings account. A return becomes relevant for credit products, for large balances, and where the bank's risk profile for your segment asks for it.
How long does activation take?
Often the same day for a straightforward file. Files with an address mismatch, an unlinked PAN or a joint holder issue take longer, and the delay is entirely documentary.
Will I lose my standing instructions and auto-debits?
Not if you redesignate rather than close and reopen. That is one of the main practical reasons to convert your existing account instead of opening a new one.
Your NRE account redesignation has a deadline.
Banks don't remind you. You need the right account stack before salary, rent, and EMIs start moving. Get the exact sequence.