W-8BEN or W-9 After Moving to India: Choose by US Tax Status
An Indian address does not determine W-8BEN eligibility. Check US-person status, the requester, treaty evidence and changed circumstances before signing.
The 60-second version
An Indian address does not determine W-8BEN eligibility. Check US-person status, the requester, treaty evidence and changed circumstances before signing.
Fast answer: an Indian address does not decide your US tax form
After moving to India, use Form W-9 if you remain a US person, including a US citizen living abroad or a resident alien. Form W-8BEN is for an eligible foreign individual documenting foreign status and, where applicable, a treaty claim. Moving your home to India does not by itself make an existing US person eligible to sign W-8BEN. Resolve your US tax classification before changing the certification on a bank or brokerage account.
The IRS instructions explicitly say that US citizens, even those living outside the United States, and other US persons should use W-9 rather than W-8BEN. A foreign mailing address, Indian PAN or RNOR position in India does not replace that classification. If you hold a green card, have substantial US presence, or are considering a treaty-residence position, obtain advice on the actual status and reporting consequences instead of treating the move date as automatic termination.
Which request are you answering?
| Your facts | Starting point | Do not assume |
|---|---|---|
| US citizen living in India | W-9 for US-person certification | An Indian address permits W-8BEN |
| Other US person, including resident alien | W-9; clarify any disputed status | A flight or account address ends residence |
| Eligible nonresident alien individual | W-8BEN when requested | Every payment receives a treaty reduction |
| Foreign entity or trust | Check the appropriate entity/intermediary form | The individual W-8BEN fits all owners |
Give the form to the requester, not the IRS
The IRS tells individuals not to send W-8BEN to the IRS. Give it to the withholding agent, payer or financial institution requesting it. A bank may provide an electronic substitute or its own secure certification workflow. Check that the request belongs to your institution before uploading a tax identifier, passport or signed certification. Keep the submitted version and the institution’s acknowledgement.
Tax certification and permission to retain an account are different questions. An institution may accept your tax form but restrict products, purchases or services for an India-resident customer. Ask separately whether you may retain the account, trade existing holdings, make new investments and receive distributions. Neither W-8BEN nor W-9 is an account-retention approval.
Foreign status and a treaty claim are not the same assertion
W-8BEN can document foreign status without establishing that every item of income qualifies for a reduced treaty rate. The instructions distinguish identifying the beneficial owner from claiming treaty benefits. A claim depends on the relevant treaty, residence, income type and applicable conditions. Do not copy another investor’s rate or put a treaty country on the form merely because it is the country of your new postal address.
Identify the payer and payment first: a dividend, interest payment, pension distribution and proceeds reported by a broker are not interchangeable. Ask which part of the form the payer needs and what documentation supports the claim. This page does not prescribe a withholding rate or determine whether a treaty position is appropriate for your circumstances.
Validity is not simply three years from the day you sign
The general IRS rule runs from the signing date through the last day of the third succeeding calendar year, unless a change in circumstances makes information incorrect. Some conditions permit indefinite validity; other documentation requirements may apply. Keep the actual signed date and the institution’s renewal instructions rather than setting a reminder exactly three years after submission.
If a change makes the submitted information incorrect, the instructions require notification to the relevant withholding agent, payer or financial institution within 30 days and a new W-8BEN or other appropriate form. Changes affecting a treaty claim matter even where a foreign-address change might not otherwise change foreign status. A calendar reminder never replaces reporting a material change promptly.
Need help with Tax & Residency?
Share your blocker in one line. Our experts will reply with practical next steps.
Build a departure-year evidence file
Save your departure date, travel history, immigration documents, existing certification, account ownership records and messages from each institution. Establish which person or entity owns each account. Joint ownership does not eliminate the need to document each owner correctly. If the institution gives inconsistent instructions, request a written clarification from its tax-documentation team before certifying under penalties of perjury.
An old W-9 should not be replaced merely to reduce withholding, and an old W-8BEN should not remain unchanged after facts that invalidate it. When status is uncertain, describe the facts to a qualified cross-border adviser and the institution. Separately consider your tax-return obligations; an account form is not a departure-year return, expatriation filing or Indian foreign-asset disclosure.
Your next steps
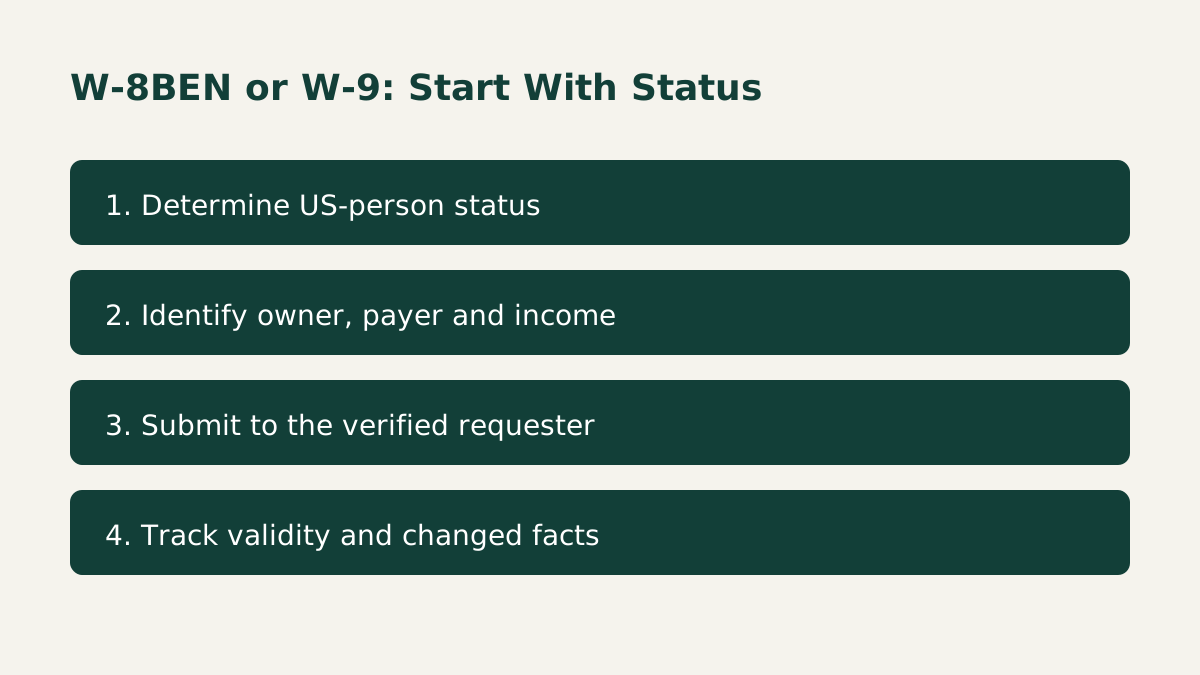
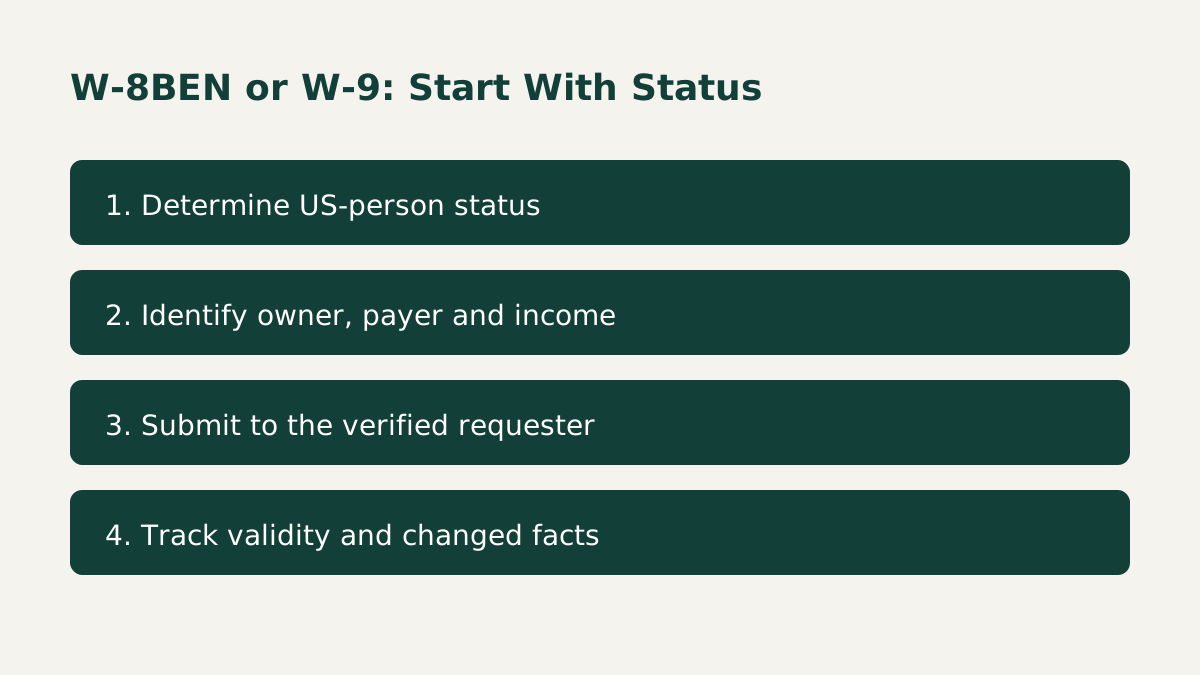
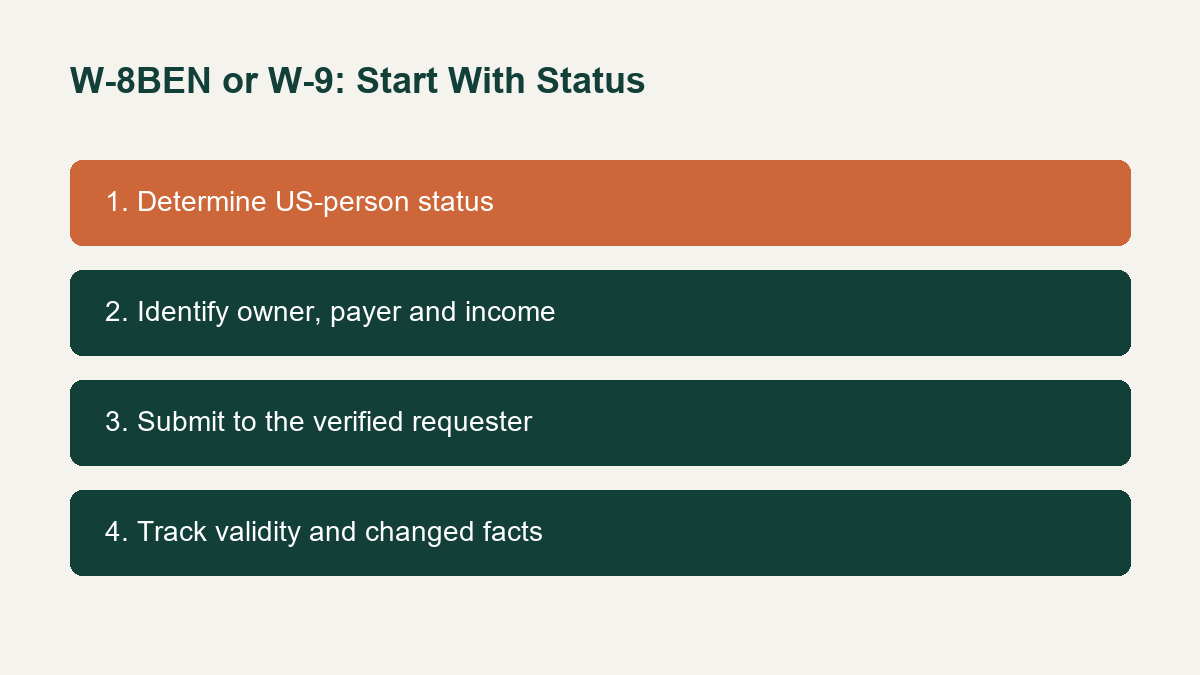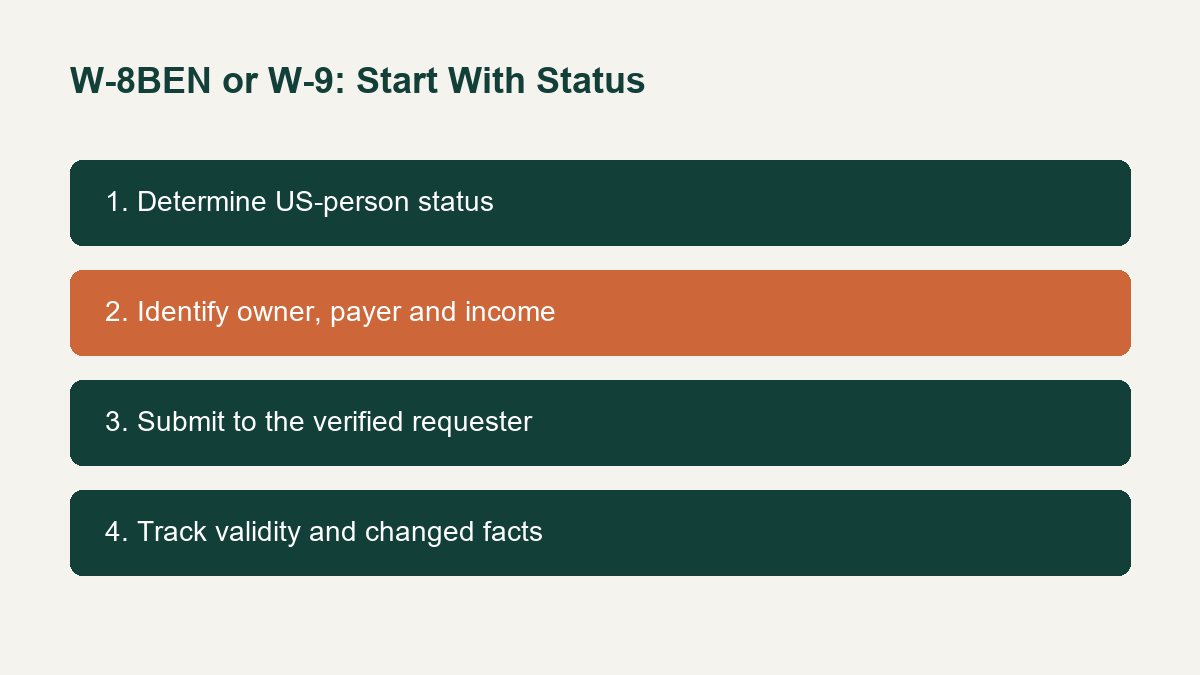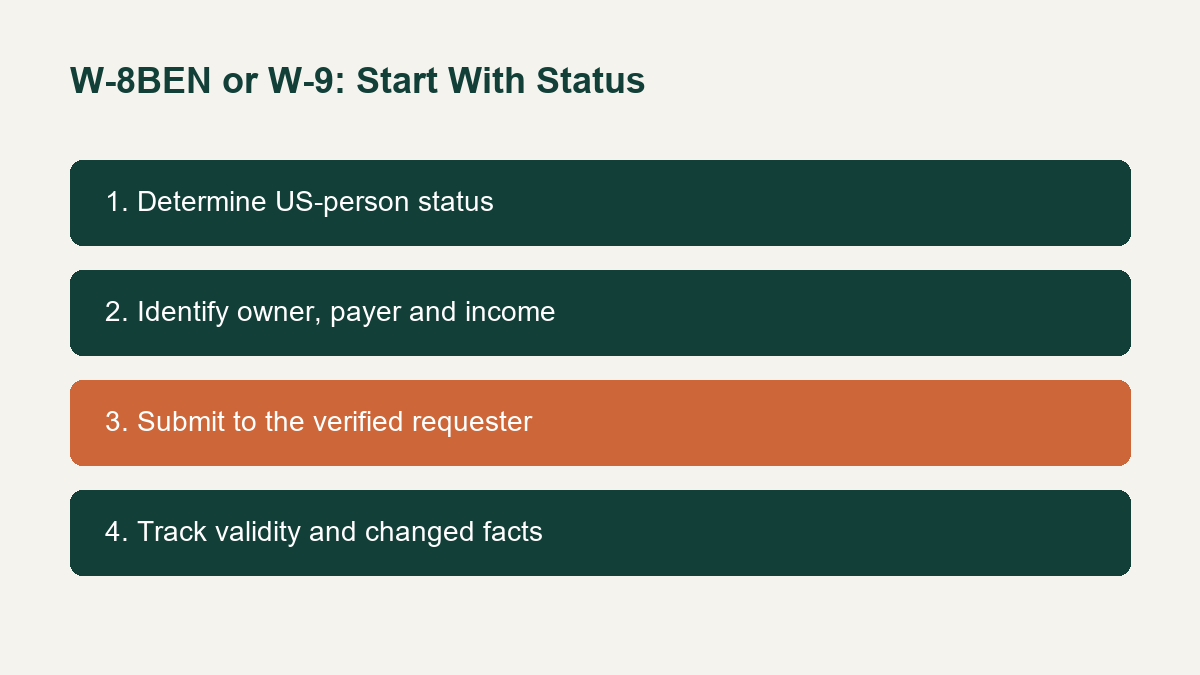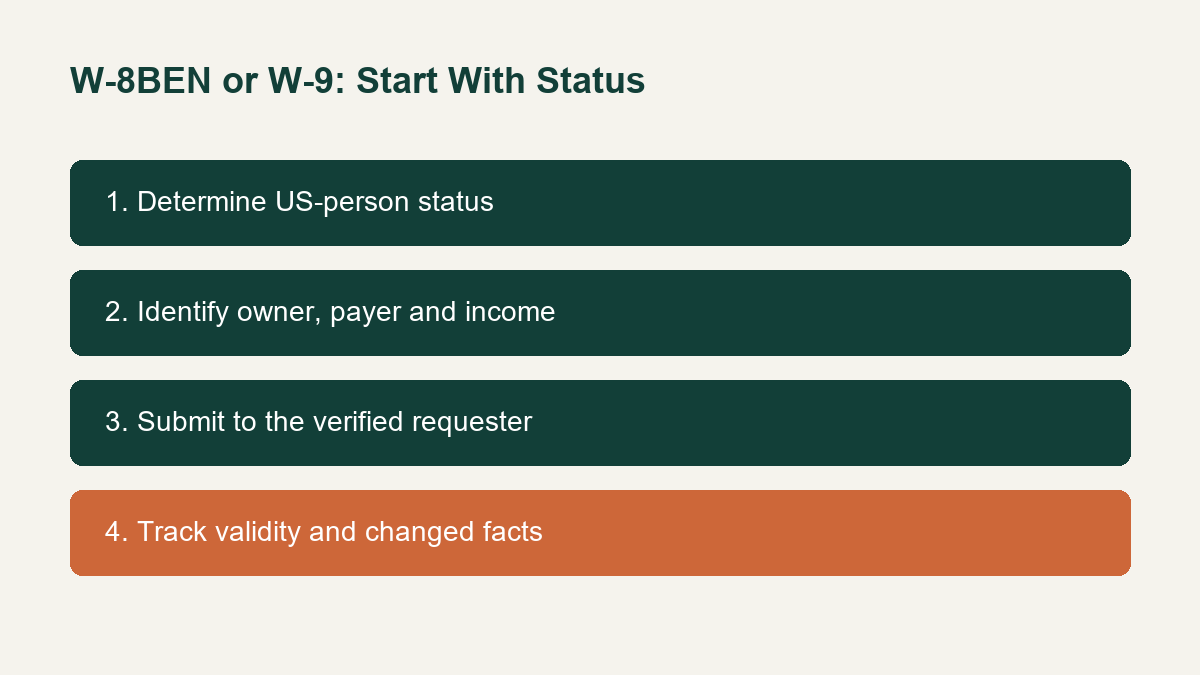
Establish status
Confirm whether you remain a US person before selecting the form.
Identify the request
Match the account owner, payer and income to the requested certification.
Submit securely
Use the verified institution channel and retain its acknowledgement.
Track changes
Record validity and notify the payer when a material circumstance changes.
Before you finish
- Confirm whether you remain a US person before selecting the form.
- Match the account owner, payer and income to the requested certification.
- Use the verified institution channel and retain its acknowledgement.
- Record validity and notify the payer when a material circumstance changes.
Need help with Tax & Residency?
Share your blocker in one line. Our experts will reply with practical next steps.
The decision at a glance
Keep the decisions in the right order
Do not treat this checklist as approval
This AI-written guide explains the decision process. The relevant institution must confirm your facts and application. It does not guarantee eligibility, tax treatment or an outcome.
Need help with Tax & Residency?
Share your blocker in one line. Our experts will reply with practical next steps.
Animated decision map
Community signal
What to watch in real discussions
Treat repeated complaints as risk signals rather than official advice. This page does not link to community search results.
Interactive checkpoint
Turn this guide into a decision file
0 of 4 checked
Can a US citizen living in India sign W-8BEN?
The IRS instructions direct a US citizen, including one living abroad, to use W-9 to document US-person status, not W-8BEN.
Do I send W-8BEN to the IRS?
No. Give it to the withholding agent, payer or financial institution requesting it.
Does W-8BEN guarantee a lower withholding rate?
No. Foreign status and eligibility for a particular treaty benefit are separate matters.
Does moving to India automatically end US tax residence?
No. Determine your classification from the applicable citizenship, immigration, residence and treaty rules.
When does W-8BEN generally expire?
Generally at the end of the third succeeding calendar year after signing, unless changed circumstances invalidate it; exceptions can apply.
What happens when my circumstances change?
If the change makes submitted information incorrect, notify the relevant requester within 30 days and provide the appropriate replacement form.
Your tax year is already running.
RNOR status, exit timing, and DTAA benefits all depend on decisions you make before you land. Don't guess.